Why the annual fee on your card keeps rising
Wondering why your credit card’s annual fee keeps climbing? Discover the factors behind these hikes and find out how to determine if your card remains a good deal.
Is your credit card becoming more costly? Keep an eye on the annual fee
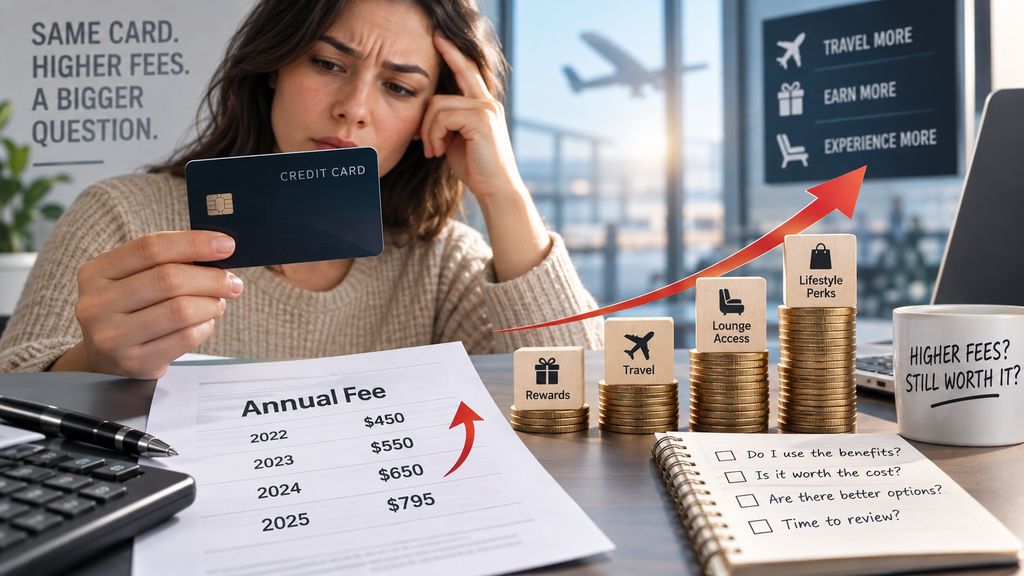
Your credit card’s annual fee might continue to rise as issuers increase prices for premium rewards, add travel and lifestyle perks, adjust the card’s financial structure, and target higher-spending users with repositioned offerings.
A bigger fee doesn’t necessarily mean the card is a better or worse choice.
The main consideration is whether the benefits you actually use justify the higher annual charge.
What Makes My Credit Card Annual Fee Go Up?
A credit card’s annual fee may rise when the issuer updates the card’s pricing or its list of benefits.
Luxury cards have been adding more travel credits, lounge access, rewards, and lifestyle perks, often accompanied by higher annual fees.
For instance, some recent updates to premium cards have driven annual fees close to or exceeding $800 each year.
The key difference lies between the value the issuer promotes and the actual benefits you end up using.
What Drives Increases in Credit Card Annual Fees?
Common reasons include the following:
- Added travel credits
- Broader airport lounge access
- Increased rewards rates
- New hotel or dining perks
- Extra statement credits
- Modifications to rewards programs
- Rising costs of premium rewards
- Shift toward targeting higher spenders
Are Annual Fees Increasing Across the Credit Card Industry?
Fee hikes have been especially notable on premium credit cards.
The Federal Reserve Bank of New York noted that U.S. credit card debt hit $1.26 trillion in Q2 2026, underscoring the ongoing significance of credit cards in managing household finances.
Among premium cards, some now carry annual fees of several hundred dollars, with a few products nearing or surpassing $800 yearly charges.
What’s Driving Annual Fee Increases on Premium Credit Cards?
Premium credit cards are increasingly competing by bundling extensive travel and lifestyle perks.
So, a higher annual fee often corresponds to a pricier set of benefits, though more perks don’t always translate into greater value for every user.
How Travel Credits Can Offset a Steep Annual Fee
Imagine a card with a $795 annual fee that offers $300 in travel credits.
The straightforward math is: $795 − $300 = $495
However, that $300 only holds its full value if you would have spent that amount on qualifying purchases regardless.
If you redeem just $150 of the credit, the real benefit is closer to $150, not the full $300.
Recognizing this difference is crucial when assessing the worth of premium credit cards.
Why Airport Lounge Access Holds Different Value for Different Travelers
Access to airport lounges can be a great perk for those who travel frequently.
For someone flying multiple times annually, lounge access might replace expenses they’d otherwise have at airports.
But if you fly only occasionally, that same perk may offer very little real benefit.
Don’t judge a perk by its listed price. Instead, consider how much money it actually saves you.
Rewards Only Matter When They Align With Your Actual Spending
A higher rewards rate can help reduce the impact of an annual fee if it applies to purchases you already plan to make.
However, spending extra just to earn rewards often undermines their value.
For instance, if a card gives bonus points on dining, charging an unnecessary $500 meal doesn’t actually save you money.
Rewards should be a result of your spending habits, not a reason to spend more.
Should You Keep a Credit Card After Its Annual Fee Goes Up?
Several important points should be weighed before choosing to keep, downgrade, or close your card.
Look at It Compared to a No-Fee Credit Card
Don’t limit your comparison to just other premium cards.
Weigh its net yearly worth against a card with no annual fee.
Check With Your Card Issuer About Switching Products
Before you decide to close your card, see if your issuer offers the option to switch to a different card instead.
Depending on your issuer and account type, you might be able to shift to a card with a reduced or no annual fee.
This option isn’t available through all issuers.
Are Credit Card Companies Allowed to Increase Your Annual Fee?
Typically, federal regulations allow certain annual or monthly maintenance fees to increase after the first year, as long as the issuer meets the required conditions.
Regulation Z along with guidance from the CFPB set the rules for notifying cardholders about specific changes to their credit card terms.
Certain modifications require 45 days’ prior notice, though the exact timing depends on the nature of the change.
How Much Advance Notice Must a Credit Card Issuer Provide?
When changes fall under Regulation Z, cardholders usually get advance notification before the new terms take effect.
The notice should clearly outline key details such as:
- The updated fee amount
- The date the change starts
- Which account terms are affected
- Any rights or choices you have
Be sure to review your issuer’s notice carefully, as rules vary by fee type and account details.
Is It Possible to Avoid Paying a Credit Card Annual Fee?
Sometimes you can. Your choices might include:
- Switching to a no-fee card offered by the same issuer;
- Checking if you can switch to a different product;
- Comparing your current card with other available cards;
- Contacting the issuer to inquire about retention offers;
- Deciding to cancel the card after weighing credit impacts.
Does Closing a Credit Card Impact Your Credit Score?
Shutting down a credit card can influence aspects that affect your credit score.
A key factor to keep in mind is credit utilization.
What Steps Should You Take If You Carry a Credit Card Balance?
If you carry a balance month after month, the annual fee isn’t the only cost you should worry about.
The Federal Reserve Bank of New York noted that U.S. credit card debt totaled $1.26 trillion in the second quarter of 2026.
For anyone carrying revolving balances, the interest charges often outweigh the benefits gained from rewards optimization.
Should You Increase Spending to Offset an Annual Fee?
Any financial estimate should never count on extra spending that you wouldn’t normally do.
When a card has a $500 annual fee, spending thousands more just to earn rewards can actually raise your costs instead of lowering them.
The aim isn’t to rack up enough rewards to make extra spending worthwhile.
Instead, focus on getting the most value from the purchases you were already planning to make.
Author’s Perspective
An increase in your credit card annual fee calls for a fresh look at the numbers, especially if the fee jumps by several hundred dollars.
The crucial factor isn’t just that the issuer added more perks. What really matters is whether those perks align with how you spend, travel, and use your card in real life.
If you’re already taking advantage of the credits and rewards, the extra fee might be balanced out by benefits you’d have bought anyway.
On the other hand, if you don’t use those benefits, the stated value can be deceptive when it comes to your personal finances.
The easiest way to judge is to ask: how much did I really save in the past year, and what was the total cost of the card?
This simple calculation offers a clearer view than relying on the promotional value assigned to each perk.
If you carry a balance, keep in mind that managing rewards should come only after you fully grasp the cost of your interest charges.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website