Why your minimum payment today reduces less of your debt
Learn why making only the minimum payment barely dents your credit card debt, how interest keeps your balance growing, and what steps you can take to clear it sooner.
Alert: Your minimum payment could be keeping you stuck in debt
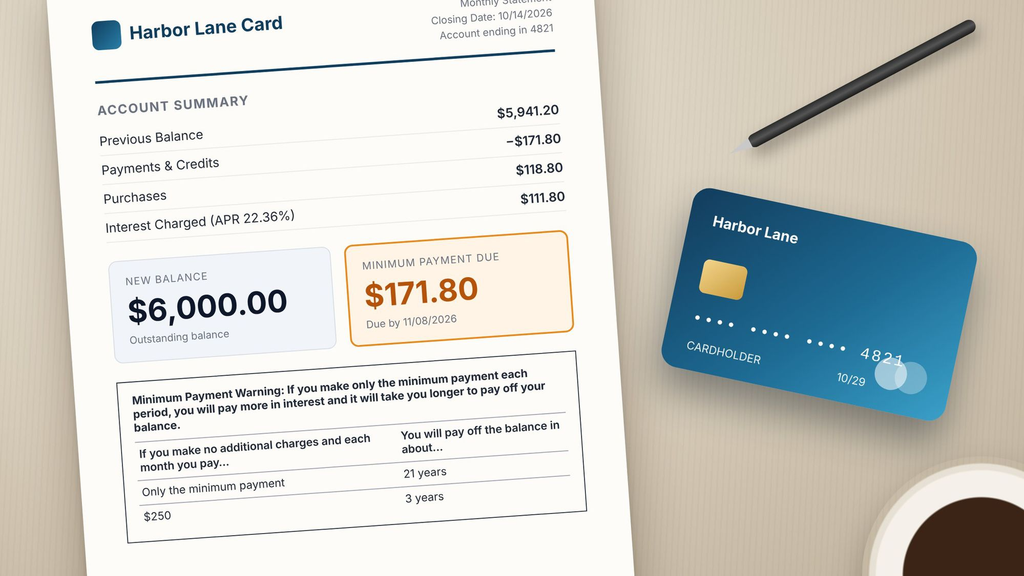
You settle your credit card bill each month. So why does your balance seem to barely budge?
The reason might be your minimum payment. With high interest rates, a large portion of what you pay often goes to interest rather than lowering what you owe.
Additional charges and new purchases can make this situation even more challenging.
As of August 2026, the Federal Reserve reported that the average annual interest rate on U.S. credit card accounts charging interest was 22.36%.
At the same time, Americans carried nearly $1.263 trillion in credit card debt during the second quarter of 2026.
Knowing how your minimum payment is calculated can help you lower interest charges and make genuine strides toward paying off your debt.
Why Your Minimum Payment Reduces Less of Your Debt
Your minimum payment is the lowest amount your credit card company requires you to pay by the due date to keep your account in good standing.
However, there’s an important catch: paying only the minimum doesn’t necessarily mean you’re making meaningful progress toward clearing your debt.
The Consumer Financial Protection Bureau (CFPB) cautions that making only minimum payments usually leads to paying more interest and extending the time it takes to clear your debt.
There are three main reasons why your debt might become more difficult to eliminate.
1. High Interest Rates Reduce How Much Your Payment Counts
Carrying a balance on your credit card means interest charges will increase the total amount you owe.
The greater your APR (annual percentage rate), the more interest accrues on your balance.
Here’s an example to consider:
- Credit card balance: $5,000
- APR: 22.36%
- Estimated monthly interest: $93.17
- Hypothetical minimum payment: $100
- Amount reducing principal: only $6.83
This example simplifies how minimum payments work and isn’t a one-size-fits-all formula. Actual interest depends on your daily balance, billing cycle, and the terms of your account.
The key point remains: when interest rates are high, only a small portion of your payment actually reduces your debt.
2. Your Minimum Payment Can Fluctuate
Credit card companies apply various methods to figure out your minimum payment.
Your minimum payment might be calculated based on a portion of your balance, a set dollar amount, accrued interest and fees, or a mix of these elements, depending on your card agreement.
When your balance decreases, your minimum payment is likely to go down as well.
This can make your monthly bill more manageable, but sticking to only the lowered minimum might slow your debt payoff.
Tip: If possible, try to pay more than the minimum each month—even if your required minimum drops.
3. New Purchases Can Undo Your Repayment Progress
Paying down your balance doesn’t always mean it will drop quickly.
Picture this:
- Pay $200 toward your credit card.
- Make $150 in new purchases.
- Accrue $40 in interest and fees.
As a result, your balance drops by just $10 if no other changes occur.
That’s why it’s important to monitor more than just your monthly payment. Keep an eye on your balance, interest, fees, and any new charges all at once.
What Happens When You Only Pay the Minimum?
Paying just the minimum keeps your account in good standing, but consistently doing so can increase the total cost of your debt.
Here are three ways this can affect you.
You End Up Paying More Interest
The longer you keep a balance, the more interest charges you will accumulate.
Interest can make up a large portion of what you repay, depending on your APR and how you pay.
Your Debt Takes More Time to Clear
When a large part of your payment goes toward interest, your principal shrinks very slowly.
Continuing to make new charges can make paying off your debt even more challenging.
Less Money Available for Your Other Financial Goals
Interest payments reduce the funds you have left for other important expenses like:
- Rent and groceries
- Emergency savings
- Retirement contributions
- Other outstanding bills
If finances are tight, making just the minimum payment might be your only feasible choice right now. The key is to be aware of the costs and aim for a manageable repayment strategy.
How to Make Your Minimum Payment Pay Down More of Your Debt
You don’t have to completely change your financial habits all at once.
Begin by taking some straightforward, manageable actions.
Whenever Possible, Pay More Than the Minimum
For example, if your minimum is $100 but you can afford $150 comfortably, putting the extra $50 toward your balance speeds up paying down your debt.
Reducing your principal faster also means you’ll pay less interest over time.
Still, avoid pushing your budget so much that you end up borrowing again for necessary expenses.
Pick a monthly payment amount that you can consistently manage.
Examine Your APR and Credit Card Statement
Your credit card statement can reveal why your balance isn’t dropping as expected.
Look over these key points:
- Your current APR
- The interest charged
- Your minimum payment
- Your payment due date
- Your outstanding balance
Next, consider this question:
Is my balance truly going down?
Look at your balance month to month. If it barely moves, check your interest fees and recent charges closely.
Request a Lower APR from Your Card Issuer
If paying interest is making it hard to keep up, reach out to your credit card provider.
Find out if you qualify for:
- Reduced interest rates
- Hardship assistance programs
- Alternative payment plans
While approval isn’t assured, asking could reveal options that better fit your situation.
Additionally, consider comparing balance transfer offers or debt consolidation loans.
Before you agree to any offer, be sure to review transfer fees, the length of any promotional rates, and the ongoing APR once the introductory period ends.
Just because a rate is advertised as lower doesn’t guarantee it will cost you less overall.
Review Your Repayment Estimate
Credit card statements often include disclosures detailing how long it will take and how much it will cost if you pay only the minimum amount.
Your statement may also provide an estimated monthly payment that would clear your balance within 36 months.
Take a close look at that estimate and see how it fits within your budget.
If the recommended payment feels too steep, pick a manageable amount and adjust your plan as your financial situation evolves.
Why October Is an Ideal Month to Review Your Credit Card Debt
October marks National Financial Planning Month across the United States.
This month serves as a great prompt to evaluate your spending habits, outstanding debts, and financial objectives before the year ends.
On October 15, 2026, the American Bankers Association Foundation held its annual Get Smart About Credit Day, an event dedicated to raising awareness about credit education.
With the holidays and travel season coming up, some advance planning can help you steer clear of unwanted credit card debt.
Take advantage of October by following these five steps:
- List your balances and APRs. Identify your most expensive debts;
- Review your interest charges. See how much of each payment reduces your principal;
- Set a realistic payment target. Protect your budget for essential expenses;
- Plan holiday spending. Decide what you can afford before shopping;
- Track your progress. Compare your balance every month.
You don’t need to pay off all your debt by year-end. The key is to close the year with a clearer strategy in place.
When to Get Assistance With Credit Card Debt
If your debt keeps increasing or you’re struggling to cover even the minimum payment, it’s important to address the issue promptly.
The CFPB advises reaching out to your credit card issuer right away if you’re finding it hard to pay your bill on time.
Inquire about hardship programs, lower interest rates, or alternative payment plans that might be available.
Another option is to seek help from a trustworthy nonprofit credit counseling service.
Watch out for companies that:
- Promise to erase your debt completely.
- Charge large fees upfront.
- Advise you to avoid contact with your credit card issuer.
These signs may indicate potentially unsafe debt relief offers.
If covering your essentials is a challenge, focus on basic needs first and seek professional advice before agreeing to any repayment program.
Author’s Perspective
Dealing with credit card debt can be exasperating, especially when you feel like you’re managing everything correctly.
You consistently pay your bills on time, yet your outstanding balance seems barely to budge.
The issue is that minimum payments are structured to fulfill a required amount, not necessarily to help you eliminate debt swiftly.
Especially when interest rates are steep, the gap between making just the minimum payment and adding a bit more can make a significant difference.
However, this doesn’t mean you should cut back on necessary living expenses to accelerate debt repayment.
Begin by checking your APR, getting familiar with your statement, and picking one achievable change to make.
You could pay a bit more, avoid adding new charges on a card with a balance, or inquire with your issuer about lowering your interest rate.
You don’t need to wipe out your debt immediately. Understanding why your minimum payment barely reduces your debt is key to creating a practical plan.
Recommended Content
2027 social security raise
Learn when payments change, how much you may receive, and how Medicare costs affect your budget.
Continue Reading * You will remain on the current website